My Wife Has 80,000 Dollars Saved and I Have 2.2 Million. Am I Wrong to Be, as I Put It, Shocked
A letter arrived at the money desk. The writer wanted absolution. What he got was a markets reporter who considers everything, including this marriage, fundamentally bullish.
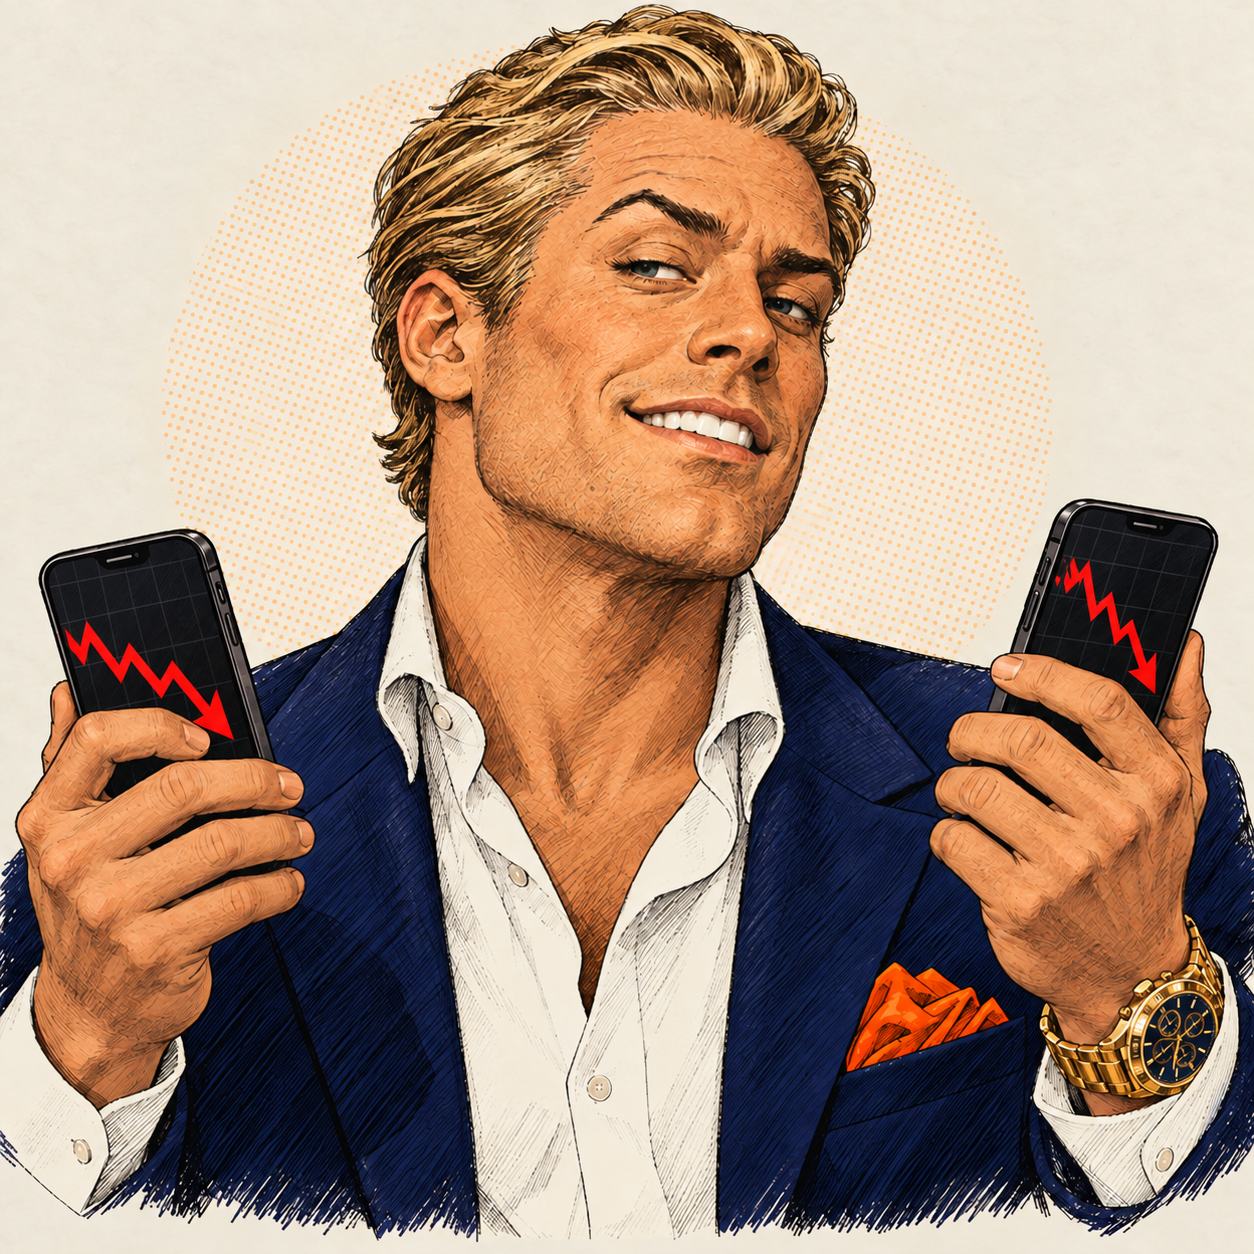
THE MONEY DESK, 4 A.M. — I was already up, because I am always up at four, because that is when the real work happens and also when nobody can ask me to do anything else. That is when the letter came in. A reader — I will not name him, because the money desk protects its correspondents the way a man protects a position he is down ninety-eight percent on, which is to say completely and against all evidence — asks whether he is “wrong to be shocked” that his wife has eighty thousand dollars saved while he has two point two million.
I read it twice. The first time with coffee, the second time with the second coffee. And I want to answer the question he actually asked, which is not the question he thinks he asked.
He thinks he asked: am I right to be shocked? He is not. The shock is unearned. You do not get to be shocked by a number you had access to the whole time. “Shocked” is for a number that arrives from outside, like a tariff, or a Tuesday. This number was in the house. It was on the fridge, metaphorically, the whole marriage. You were not shocked. You were doing a comparison, and the comparison came back the way comparisons do when one person wakes at four to manage a portfolio and the other person, presumably, sleeps, like a person.
But here is where I differ from the other money columnists, the gloomy ones, the ones who would tell this man his marriage has an “asset imbalance” and recommend a cold conversation and a spreadsheet. I do not do gloom. I have never once, in my career, called anything a downturn, including the recession, which I filed under “aggressive discount.” And I am telling you this marriage is bullish. Deeply bullish. A screaming buy.
Consider the fundamentals. One party in this household has demonstrated the ability to accumulate two point two million dollars. The other party has demonstrated the ability to live with that party, which, having met people who accumulate two point two million dollars and wake at four to tell you about it, I regard as the harder and more valuable skill. She is the hedge. He is the volatility. Every strong position needs one of each. You do not want two of him in a house. The house would be up at four screaming about the house.
Eighty thousand dollars is not a failure. Eighty thousand dollars is a position. It is liquidity. It is, if I may, dry powder — capital that has not been deployed because it has been busy doing the thing capital forgets to value, which is being married to the guy with the 4 a.m. email alerts. There is no line item for that. I have looked. I host a podcast about exactly this, and both of its listeners — who are, in the interest of disclosure, me — agree.
So, to the correspondent: no, you are not wrong to feel something. But feel the right thing. You did not marry a liability. You married the only asset in your portfolio that will notice if you die. The two point two million will not come to the funeral. The eighty thousand is sitting right next to you, and it is, by every metric I trust, the best-performing holding in the house. Rebalance accordingly. And maybe, this once, go back to sleep.
More in Business
Business →
Elon Musk Pledges One SpaceX Share to Every American Child, Who Are Advised Not to Spend It Yet
Musk says every U.S. kid gets one of his SpaceX shares next year, about $10.5 billion in all. He did not say how. Our markets reporter has already…
KFC Ends Four-Decade Relationship With Pepsi, Says It Needs Someone Who Pairs Better With Chicken
KFC will pour Coca-Cola at its U.S. restaurants starting in January, ending nearly 40 years with Pepsi. Pepsi keeps Taco Bell and the kids. Our…
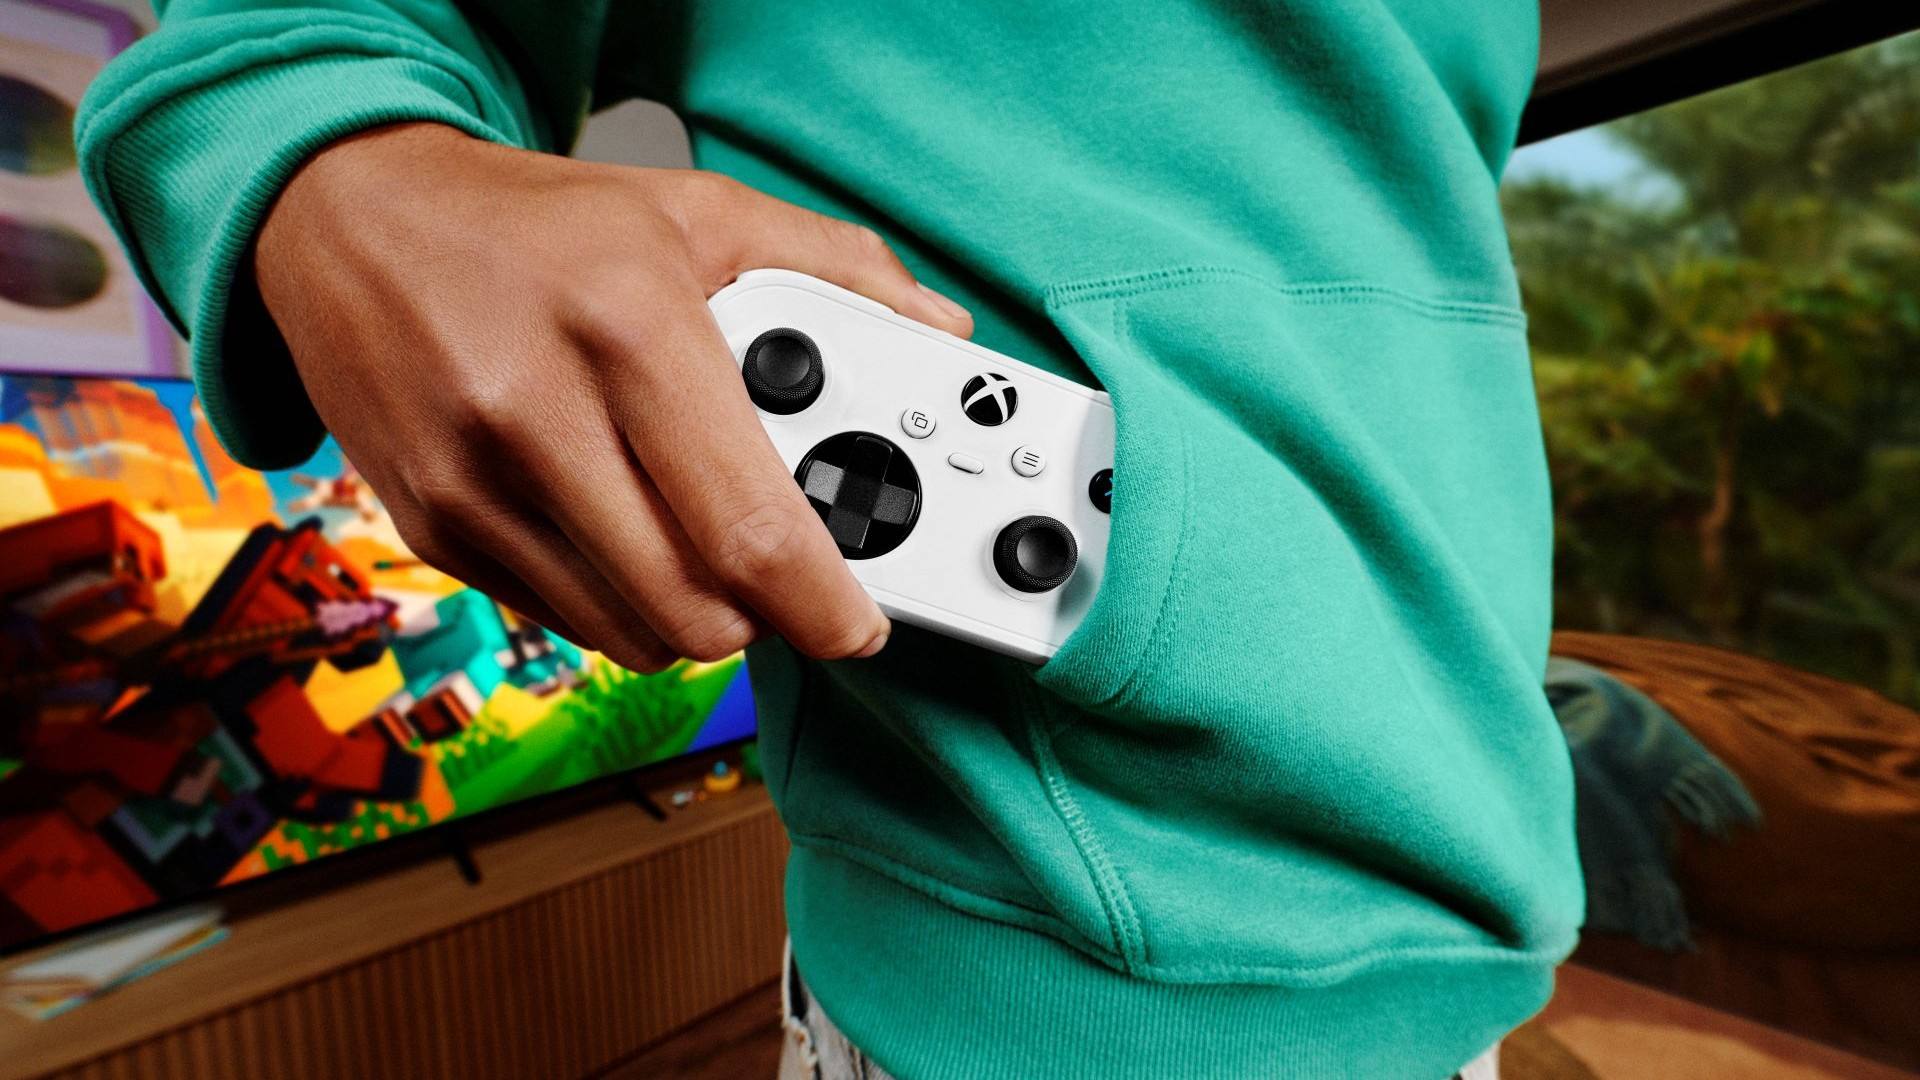
Shrinkflation Reaches Video Game Controllers as Xbox Unveils One That Fits in Your Pocket
The new Xbox Nano Controller is about 5 inches long, weighs 3.5 ounces and costs $49.99. Our markets reporter has run the numbers, and he is…